

PV Function (Calligra Sheets)
Calculate present value with Calligra’s actual annuity interface, including payment timing, cash-flow signs and the zero-rate implementation limitation.
Verification status: See the evidence and test scope described in this guide. How formula examples are checked
Quick answer: =PV(0.08;2;0;-1166.4) is independently expected to return 1000: the present-value magnitude of a 1,166.40 future cash flow discounted over two periods at 8%.
Two Calligra-specific cautions: The older handbook’s three-argument order is stale, and the inspected implementation has no zero-rate branch. Do not assume PV(0;12;-100) returns the mathematically correct 1200.
Availability and verification scope
- Introduced: Original introduction release not established. The checked release is not an introduction date.
- Available in source: Calligra Sheets 26.08.2, checked against first-party released source retrieved on October 18, 2026.
- Retired or deprecated: Neither retirement nor deprecation is established; the runtime registration remains present.
- Evidence: The selected formulas in the native-results section were executed in Calligra Sheets 25.04.2 on October 18, 2026, and read back from its saved ODS. Other numerical derivations are independent calculations. Version 26.08.2 was source-checked, not executed. These checks do not establish general Excel import or workbook round-trip compatibility.
- Entry style: English function names, semicolon separators and decimal points. Optional-argument brackets are explanatory and are not entered in a formula.
Native results in Calligra Sheets 25.04.2
These selected formulas were recalculated in the native application. Display precision can differ from the independent arithmetic above.
| Formula | Native displayed result |
|---|---|
=PV(0.08;2;0;-1166.4) |
1000.0000000000 |
=PV(0.01;12;-100) |
1125.5077473485 |
=PV(0.01;12;-100;0;1) |
1136.7628248219 |
=PV(0.01;12;100) |
-1125.5077473485 |
=PV(0;12;-100) |
nan |
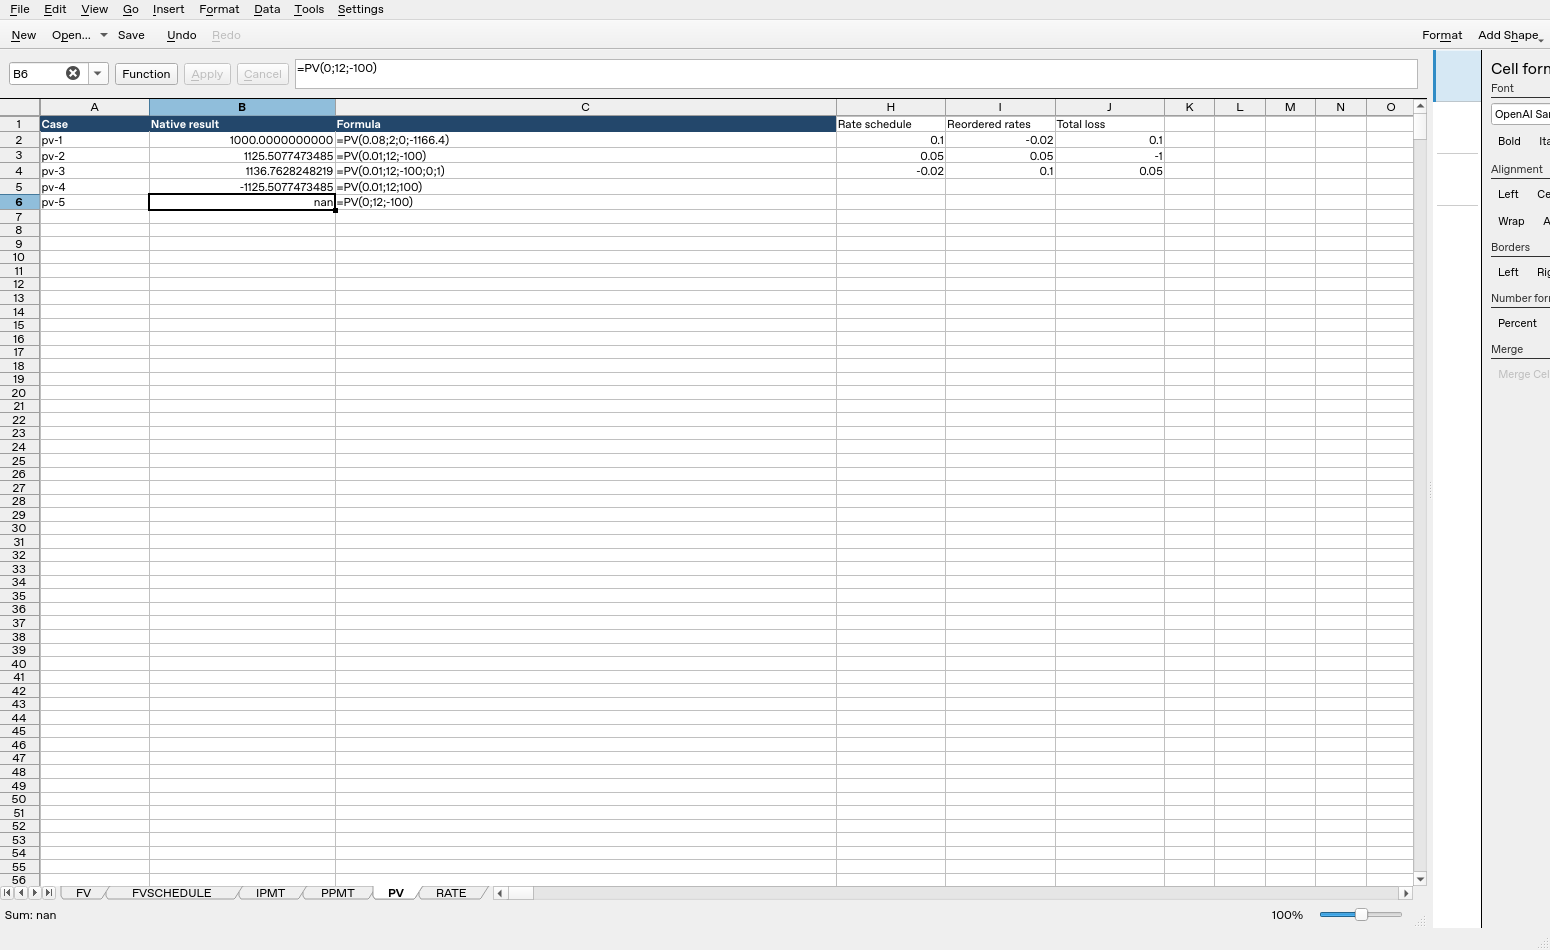
Calligra Sheets 25.04.2: cell B6 evaluates =PV(0;12;-100) to nan. Column B contains calculated results; column C shows formula text. Columns were resized and unused columns hidden for readability after the result workbook was saved; the screenshot layout differs from that saved layout, while formulas, inputs and results are unchanged.
Syntax and arguments
=PV(rate; periods; payment[; future_value[; type]])
| Argument | Meaning and default |
|---|---|
| rate | Required discount/interest rate per period |
| periods | Required number of equal periods |
| payment | Required constant signed payment per period; use 0 if none |
| future_value | Optional signed future cash flow, default 0 |
| type | Optional timing selector, default 0 for end-of-period; 1 for beginning-of-period |
The registration accepts three through five arguments. The older PV handbook entry describes PV(future value;rate;periods), but the released body uses the annuity order above. This discrepancy is not a second supported overload. Enter the actual rate first.
Cash-flow signs are part of the equation. For an ordinary loan, positive present value is funds received now and negative payments are repayments. For an investment valuation, a positive future receipt convention can imply a negative present cash flow. Choose and label one consistent perspective.
Build a monthly-payment valuation
On a fresh worksheet enter 0.01 in B1, 12 in B2, −100 in B3, 0 in B4 and 0 in B5. Label them periodic rate, periods, payment, terminal flow and timing.
- In B7 enter
=PV(B1;B2;B3;B4;B5). - Independently expect 1125.5077473485, approximately 1125.51 in currency display.
- The undiscounted payments total 1200 in magnitude. Their present value is lower because each end-period payment is discounted.
- Independently sum
100/1.01 + 100/1.01^2 + … + 100/1.01^12. This gives the same expected value without using PV.
The annuity expression is 100×(1−1.01^(−12))/0.01. Keep full precision while checking. The function does not round every discount factor or payment to cents.
Timing and sign controls
| Formula | Independent expectation |
|---|---|
=PV(0.01;12;-100) |
1125.5077473485 |
=PV(0.01;12;-100;0;1) |
1136.7628248219 |
=PV(0.01;12;100) |
−1125.5077473485 |
=PV(0.08;2;0;-1166.4) |
1000 |
Beginning-period payments occur one interval earlier, so their present-value magnitude is multiplied by 1.01. Changing every payment’s sign reverses the returned present-value sign. The lump-sum example discounts 1166.4 by 1.08^2, and the negative future input produces a positive present result.
Advanced case: combine recurring payments with a terminal flow
The implementation separates two components: the discounted terminal flow and the discounted payment annuity. For nonzero r, define G=(1+r)^n and S=(G−1)/r. It returns (-future_value − payment×(1+r×type)×S)/G.
This decomposition lets you reconcile a valuation containing both periodic payments and a final amount. Verify each component separately with its sign before adding them. Do not treat future_value as an extra payment at every period; it is one terminal cash flow.
The initial 1000/two-period example also pairs with the future-value check =FV(0.08;2;0;-1000), whose independent magnitude is 1166.4. The signs are selected consistently for each direction. A numerical inverse check should compare the intended cash-flow equation, not blindly reuse the same sign in every argument.
Zero-rate implementation gap
The body calculates ((1+rate)^periods−1)/rate directly. At rate 0 this becomes 0/0, and the resulting nonfinite arithmetic is not replaced with the mathematical limit. For =PV(0;12;-100), Calligra Sheets 25.04.2 displayed exactly nan and saved a floating-point nan value. This is a nonfinite result, not the mathematically correct limit of 1200 and not a conventional spreadsheet error code.
Mathematically, with zero interest, present value is −future_value − payment×periods. For the example that is 1200. A zero-rate model can calculate that direct sum separately; it must not mislabel it as an observed PV result. The source’s only explicit zero-growth-factor guard concerns G==0, which is a different condition.
For very small nonzero rates, the direct subtraction in G−1 can also lose precision. Do not assume a near-zero result is as reliable as an independently evaluated limit simply because it is finite.
Other boundaries
The body does not fully validate type, term or the real-number domain of the power calculation. Use type 0/1 and sensible positive periods. A rate of −1 can make the growth factor zero and enter the internal division-by-zero error branch; other negative-base/fractional-power cases need separate checks.
Text coercion, unsupported type values, extreme magnitudes and imported errors are not covered by the ordinary examples. The function does not model varying payments, irregular dates, fees or taxes. Use a separate cash-flow schedule when those details matter.
Compatibility and related functions
No explicit alternate function name is registered for this function in the inspected Financial module. Matching a name or mathematical identity does not establish identical coercion, invalid-input behavior, file import/export or availability in every packaged build.
- PMT solves the payment for an annuity model.
- POWER supports independent discounting.
- SUM can total individually discounted flows.
- Released implementation provides the calculation and validation details.